Zurich - The textile machinery sector remained the most positive part of the industry in July with several downstream sectors reporting a plunge into negative territory, according to a new ITMF report.
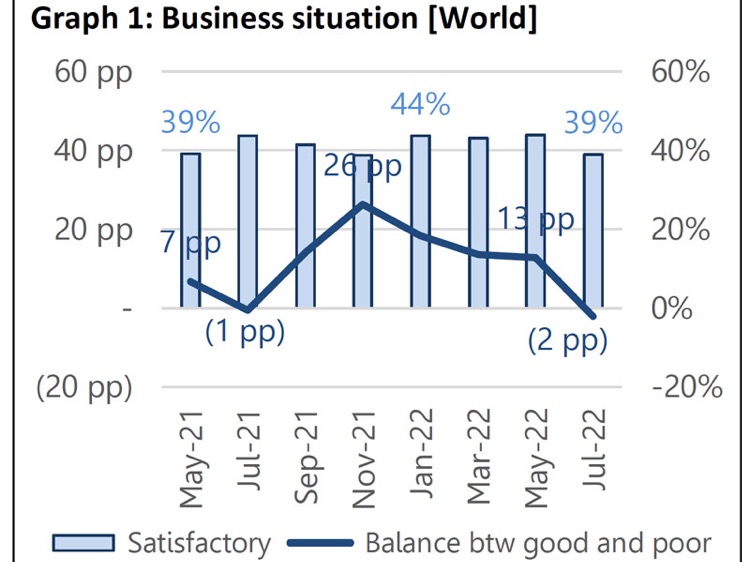
The 15th ITMF Corona-Survey shows that the business situation for textile machinery was the only segment still in positive territory in July with business expectations in most other parts of the supply chain turning negative for the first time since the start of survey in May 2021.
Order intake is weakening globally but is still in positive territory. Here too, expectations have turned negative in all textile segments except for textile machinery producers. A difficult period is to be expected ahead. Order intake is deteriorating in all Asian regions and stable in North America, South America, and Africa.
Order backlog has been slightly decreasing in the past few months, from a maximum of 3.1 months in March 2022 to 2.9 months in July. It is expected to continue falling until March 2023. Capacity utilization rate has been stagnating since the beginning of 2022, on average. This indicator is rising in Africa and North and Central America. South Asia reports a strong decrease in capacity utilization, so do fibre and home textile producers as well as spinners.
While high prices for raw materials, energy, and logistics are still regarded as major supply side concerns, they have somewhat eased compared to May 2022. The prospects of weakening demand caused by surging inflation are worrisome, the survey said.